Papa John's franchise: SBA loan record
Of the 126 SBA 7(a) loans to Papa John's franchisees that were approved in FY2012–FY2021 and disbursed, 14 were later charged off: 11.1% (95% interval 6.7–17.8%). That is not clearly different from the 7.7% rate for all franchise-coded loans in the same period.
How Papa John's compares
Measured against every SBA 7(a) loan in Limited-Service Restaurants for the same years, Papa John's's charge-off rate is not clearly different from the industry's 8.2%. "Higher" or "lower" is stated only when the two confidence intervals do not overlap. By loan dollars, 8.6% of the $39M disbursed in FY2012–FY2021 was charged off ($3.4M).
Loans by approval year
Paid in fullCharged offStill active
| Approval year | Approved | Disbursed | Paid in full | Charged off | Still active | Charged off % |
|---|---|---|---|---|---|---|
| FY2012 | 11 | 10 | 9 | 1 | 0 | 10.0% |
| FY2013 | 8 | 6 | 5 | 1 | 0 | — |
| FY2014 | 7 | 7 | 6 | 1 | 0 | — |
| FY2015 | 21 | 20 | 19 | 1 | 0 | 5.0% |
| FY2016 | 13 | 11 | 8 | 2 | 1 | 18.2% |
| FY2017 | 20 | 20 | 14 | 3 | 3 | 15.0% |
| FY2018 | 21 | 18 | 12 | 4 | 2 | 22.2% |
| FY2019 | 10 | 7 | 5 | 1 | 1 | — |
| FY2020 | 13 | 12 | 9 | 0 | 3 | 0.0% |
| FY2021 | 19 | 15 | 8 | 0 | 7 | 0.0% |
| FY2022 (recent) | 6 | 5 | 3 | 1 | 1 | — |
| FY2023 (recent) | 7 | 7 | 1 | 0 | 6 | — |
| FY2024 (recent) | 10 | 9 | 2 | 0 | 7 | — |
| FY2025 (recent) | 6 | 5 | 0 | 0 | 5 | — |
| FY2026 (recent) | 6 | 3 | 0 | 0 | 3 | — |
Recent years look better than they will end up: most charge-offs happen two to six years after approval. Single-year rates are shown only for years with at least 10 disbursed loans.
Full record, FY1991–FY2026
| Outcome | Loans | Share of disbursed |
|---|---|---|
| Paid in full | 190 | 69.9% |
| Charged off | 43 | 15.8% |
| Still active (status withheld by SBA) | 39 | 14.3% |
| Disbursed | 272 | 100% |
| Approved but cancelled | 44 | — |
| Approved, not yet disbursed | 4 | — |
Total charged off over the full record: $11,374,122 of $92,166,345 disbursed.
Charge-offs by calendar year
| Year charged off | Loans | Amount |
|---|---|---|
| 2016 | 7 | $2,445,484 |
| 2017 | 1 | $402,621 |
| 2018 | 3 | $824,100 |
| 2019 | 2 | $194,976 |
| 2020 | 1 | $234,182 |
| 2021 | 3 | $493,164 |
| 2022 | 4 | $505,873 |
| 2025 | 2 | $179,373 |
| 2026 | 1 | $1,183,363 |
Recent lending, FY2022–FY2026
Estimate the payment on a loan this size with the loan payment calculator, or compare Papa John's with other brands.
Lenders that finance Papa John's franchisees
47 lenders made SBA 7(a) loans coded to Papa John's since FY2017. A lender that already knows a brand has usually reviewed its franchise agreement before.
| Lender | Loans since FY2017 | Total approved | Latest |
|---|---|---|---|
| The Huntington National Bank | 11 | $4.9M | FY2024 |
| Byline Bank | 9 | $5.9M | FY2026 |
| United Business Bank | 9 | $5.0M | FY2024 |
| Wells Fargo Bank National Association | 9 | $2.7M | FY2018 |
| Royal Business Bank | 4 | $4.6M | FY2025 |
| Bank of Hope | 4 | $365K | FY2018 |
| Live Oak Banking Company | 3 | $6.0M | FY2026 |
| Vallant Bank | 3 | $709K | FY2024 |
| JPMorgan Chase Bank, National Association | 3 | $450K | FY2021 |
| Santander Bank, National Association | 3 | $367K | FY2025 |
Where the loans are
- California · 26
- Illinois · 10
- Ohio · 8
- New York · 7
- Minnesota · 6
- Georgia · 5
- Pennsylvania · 4
- Michigan · 3
Loans by project state since FY2017.
SBA Franchise Directory status
Listed Papa John's · identifier S1273 · effective October 1, 2017
Meets the FTC definition of a franchise: yes.
SBA note: When the real estate where the franchise business is located will secure the SBA-guaranteed loan, the Addendum to Lease may not be executed.
Other Limited-Service Restaurants franchises
| Brand | Loans, FY2012–FY2021 | Charged off | 95% interval |
|---|---|---|---|
| Subway | 1,115 | 7.4% | 6.0–9.1% |
| Jimmy John's | 601 | 6.5% | 4.8–8.7% |
| Firehouse Subs | 430 | 7.7% | 5.5–10.6% |
| Dairy Queen | 389 | 1.0% | 0.4–2.6% |
| Little Caesars | 351 | 6.3% | 4.2–9.3% |
| Marco's Pizza | 337 | 5.6% | 3.6–8.6% |
| Jersey Mike's Subs | 321 | 1.6% | 0.7–3.6% |
| Tropical Smoothie Cafe | 302 | 2.0% | 0.9–4.3% |
Questions
What is the SBA loan charge-off rate for Papa John's franchises?
11.1% of disbursed SBA 7(a) loans approved in FY2012–FY2021 (14 of 126), with a 95% confidence interval of 6.7–17.8%. Data as of September 30, 2026.
How large is a typical SBA loan for Papa John's?
The median SBA 7(a) loan approved in FY2022–FY2026 was $380,000 at an initial interest rate of 9.75% over 120 months.
Which lenders make SBA loans to Papa John's franchisees?
Since FY2017, 47 lenders have made SBA 7(a) loans coded to Papa John's. The most active were The Huntington National Bank, Byline Bank, United Business Bank.
Is Papa John's on the SBA Franchise Directory?
Yes. Papa John's is listed on the SBA Franchise Directory under identifier S1273, effective October 1, 2017.
Cite or embed
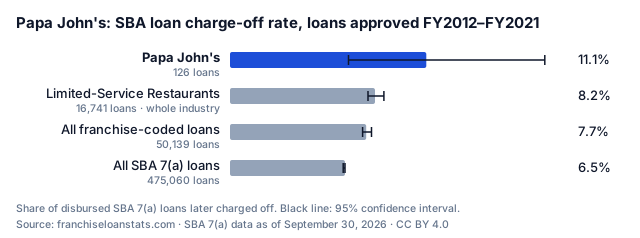
Figures and chart are free to reuse under CC BY 4.0 with credit and a link. The full table is on the data page.
What these numbers do and do not mean
- A charge-off means the SBA wrote off a loan balance. It is not the same as a location closing, and a closed location does not always produce a charge-off.
- Only loans that lenders coded to this brand in the SBA file are counted. Franchisees who paid cash, borrowed conventionally or whose loan was coded differently are not here.
- Loan outcomes reflect the borrower, the site, the lender and the economy as well as the brand. Past loans do not predict any future loan.
- Matching: matched to the SBA Franchise Directory, with 2 older codes merged in. Source names: PAPA JOHN'S PIZZA; Papa John's.
Source: SBA 7(a) FOIA loan data as of September 30, 2026, U.S. Government work. Full methodology. Spot an error? Tell us.