Scout & Molly's franchise: SBA loan record
Of the 21 SBA 7(a) loans to Scout & Molly's franchisees that were approved in FY2012–FY2021 and disbursed, 4 were later charged off: 19.0% (95% interval 7.7–40.0%). That is not clearly different from the 7.7% rate for all franchise-coded loans in the same period. With fewer than 30 loans the estimate is rough, so this brand is not ranked.
How Scout & Molly's compares
Measured against every SBA 7(a) loan in Women's Clothing Stores for the same years, Scout & Molly's's charge-off rate is not clearly different from the industry's 11.9%. "Higher" or "lower" is stated only when the two confidence intervals do not overlap. By loan dollars, 9.5% of the $4.3M disbursed in FY2012–FY2021 was charged off ($407K).
Loans by approval year
Paid in fullCharged offStill active
| Approval year | Approved | Disbursed | Paid in full | Charged off | Still active | Charged off % |
|---|---|---|---|---|---|---|
| FY2015 | 3 | 2 | 2 | 0 | 0 | — |
| FY2016 | 7 | 7 | 3 | 4 | 0 | — |
| FY2017 | 9 | 9 | 6 | 0 | 3 | — |
| FY2018 | 2 | 2 | 1 | 0 | 1 | — |
| FY2019 | 1 | 1 | 1 | 0 | 0 | — |
Recent years look better than they will end up: most charge-offs happen two to six years after approval. Single-year rates are shown only for years with at least 10 disbursed loans.
Full record, FY2015–FY2019
| Outcome | Loans | Share of disbursed |
|---|---|---|
| Paid in full | 13 | 61.9% |
| Charged off | 4 | 19.0% |
| Still active (status withheld by SBA) | 4 | 19.0% |
| Disbursed | 21 | 100% |
| Approved but cancelled | 1 | — |
| Approved, not yet disbursed | 0 | — |
Total charged off over the full record: $406,543 of $4,297,100 disbursed.
Charge-offs by calendar year
| Year charged off | Loans | Amount |
|---|---|---|
| 2018 | 2 | $244,029 |
| 2019 | 1 | $59,112 |
| 2020 | 1 | $103,403 |
Lenders that finance Scout & Molly's franchisees
4 lenders made SBA 7(a) loans coded to Scout & Molly's since FY2017. A lender that already knows a brand has usually reviewed its franchise agreement before.
| Lender | Loans since FY2017 | Total approved | Latest |
|---|---|---|---|
| Stearns Bank National Association | 9 | $1.8M | FY2019 |
| PNC Bank, National Association | 1 | $350K | FY2017 |
| Wells Fargo Bank National Association | 1 | $313K | FY2018 |
| Happen Bank | 1 | $310K | FY2017 |
Where the loans are
Loans by project state since FY2017.
SBA Franchise Directory status
Listed Scout & Molly's · identifier S1536 · effective October 1, 2017
Meets the FTC definition of a franchise: yes.
Other Women's Clothing Stores franchises
| Brand | Loans, FY2012–FY2021 | Charged off | 95% interval |
|---|---|---|---|
| Apricot Lane | 31 | 16.1% | 7.1–32.6% |
Questions
What is the SBA loan charge-off rate for Scout & Molly's franchises?
19.0% of disbursed SBA 7(a) loans approved in FY2012–FY2021 (4 of 21), with a 95% confidence interval of 7.7–40.0%. Data as of September 30, 2026.
Which lenders make SBA loans to Scout & Molly's franchisees?
Since FY2017, 4 lenders have made SBA 7(a) loans coded to Scout & Molly's. The most active were Stearns Bank National Association, PNC Bank, National Association, Wells Fargo Bank National Association.
Is Scout & Molly's on the SBA Franchise Directory?
Yes. Scout & Molly's is listed on the SBA Franchise Directory under identifier S1536, effective October 1, 2017.
Cite or embed
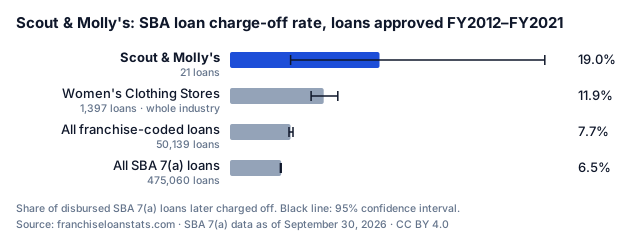
Figures and chart are free to reuse under CC BY 4.0 with credit and a link. The full table is on the data page.
What these numbers do and do not mean
- A charge-off means the SBA wrote off a loan balance. It is not the same as a location closing, and a closed location does not always produce a charge-off.
- Only loans that lenders coded to this brand in the SBA file are counted. Franchisees who paid cash, borrowed conventionally or whose loan was coded differently are not here.
- Loan outcomes reflect the borrower, the site, the lender and the economy as well as the brand. Past loans do not predict any future loan.
- Matching: matched to the SBA Franchise Directory, with 1 older code merged in. Source names: Scout & Molly's.
Source: SBA 7(a) FOIA loan data as of September 30, 2026, U.S. Government work. Full methodology. Spot an error? Tell us.